

Want to bookmark your favourite articles and stories to read or reference later? Start your Independent Membership today.
Already a member?
Log in
Around three in 10 home insurance claims are rejected by home insurance providers, according to data from the Financial Conduct Authority.
The low acceptance rates may, in part, be driven by confusion over what customers can claim for their policies – and not reading the T&Cs.
“We always tell customers not to leave their home insurance on auto-renew and to always shop around,” says Tamzin Metcalfe, home insurance expert at Go.Compare.
Once you find a suitable policy, she emphasises the importance of always reading the fine print.
“All the exclusions will be listed and there might be a lot of stuff in the fine print, so make sure that you read everything properly,” advises Metcalfe.
Here are 10 common home insurance myths that can trip people up…
Myth 1: My dripping tap has caused a flood but it’s covered by my insurer
“Accidental damage is only included as standard on 23% of home insurance policies,” reveals Metcalfe. “But even if you do add it as an optional extra, it won’t cover you for damage caused by pests or shoddy workmanship. So, if you take on an ambitious DIY project yourself, such as rewiring the house, and it goes wrong, your claim is unlikely to be accepted.”
Metcalfe highlights that accidental damage in home insurance means a sudden, unexpected, and unintentional one-off physical incident, and excludes gradual deterioration or general wear and tear.
“For example, if your tap has been broken because of lack of maintenance, any claim you would try to make would be rejected because the issue should have been sorted originally. But if it bursts and floods your kitchen, then you will be covered,” she explains.
Myth 2: My home insurance covers my property while I’m on my round-the-world trip

Invest at least £100 in Stocks or ETFs of your choice. Get fractional shares worth £50!
Terms and conditions apply.
ADVERTISEMENT
Invest at least £100 in Stocks or ETFs of your choice. Get fractional shares worth £50!
Terms and conditions apply.
ADVERTISEMENT
“Most home insurance providers will only cover your property if it’s empty for between 30 and 60 consecutive days,” says Metcalfe. “When your home is unoccupied it increases the risk of break-ins and if something like a pipe bursts it is more likely to do more damage because nobody’s there to notice it.”
Therefore, if you know you will be away for an extended period of time, Metcalfe recommends letting your insurer know.
“They might be able to extend your cover, or you could get a specialist unoccupied home insurance cover,” says Metcalfe.
Myth 3: I won’t have to pay anything if my insurance claim is accepted
“This is quite a common misconception, but it is the same for any type of insurance,” says Metcalfe. “If you make a claim and it’s accepted, you still have to pay your excess amount.
“For example, if you make a claim for £2,000 and the excess was £200, you’ll only get £1,800 from the insurance company.”
Myth 4: My watch has gone missing but I can make a claim
“If something went missing and you’re not sure if you lost it or it was stolen it can be difficult to know what to do when it comes to insurance,” says Metcalfe. “Without proof, insurance companies call it a ‘mysterious disappearance’ and usually refuse to pay.”
To get a claim approved, she recommends providing receipts.
“You will need to show proof that you owned it (like a receipt or photo), proof it existed recently before it went missing, details of what happened when it was lost or a police report if it was stolen,” says Metcalfe.
Myth 5: My bike and mobile phone are covered while I’m away from home
“Only 15% of contents insurance policies have personal possessions cover included as standard. So, if you want cover for your bike or mobile when you’re out, you’ll need it as an optional add-on,” explains the insurance expert.
“If you have a really expensive bike it might be worth getting specific bicycle insurance, but an average bike could probably just be included on your contents insurance.”
She adds: “If you’re concerned about expensive items not being covered, then list them separately on the contents insurance, or get separate gadget insurance.”
Myth 6: I live in a flood-risk area so insuring my contents will be too expensive
“If you live in a flood-risk area the Flood Re scheme lets people access affordable home insurance even if their home has flooded in the past and pay a lower rate than they normally would if they have a past claims history,” explains Metcalfe.
Myth 7: My garden fences will be covered from storm damage
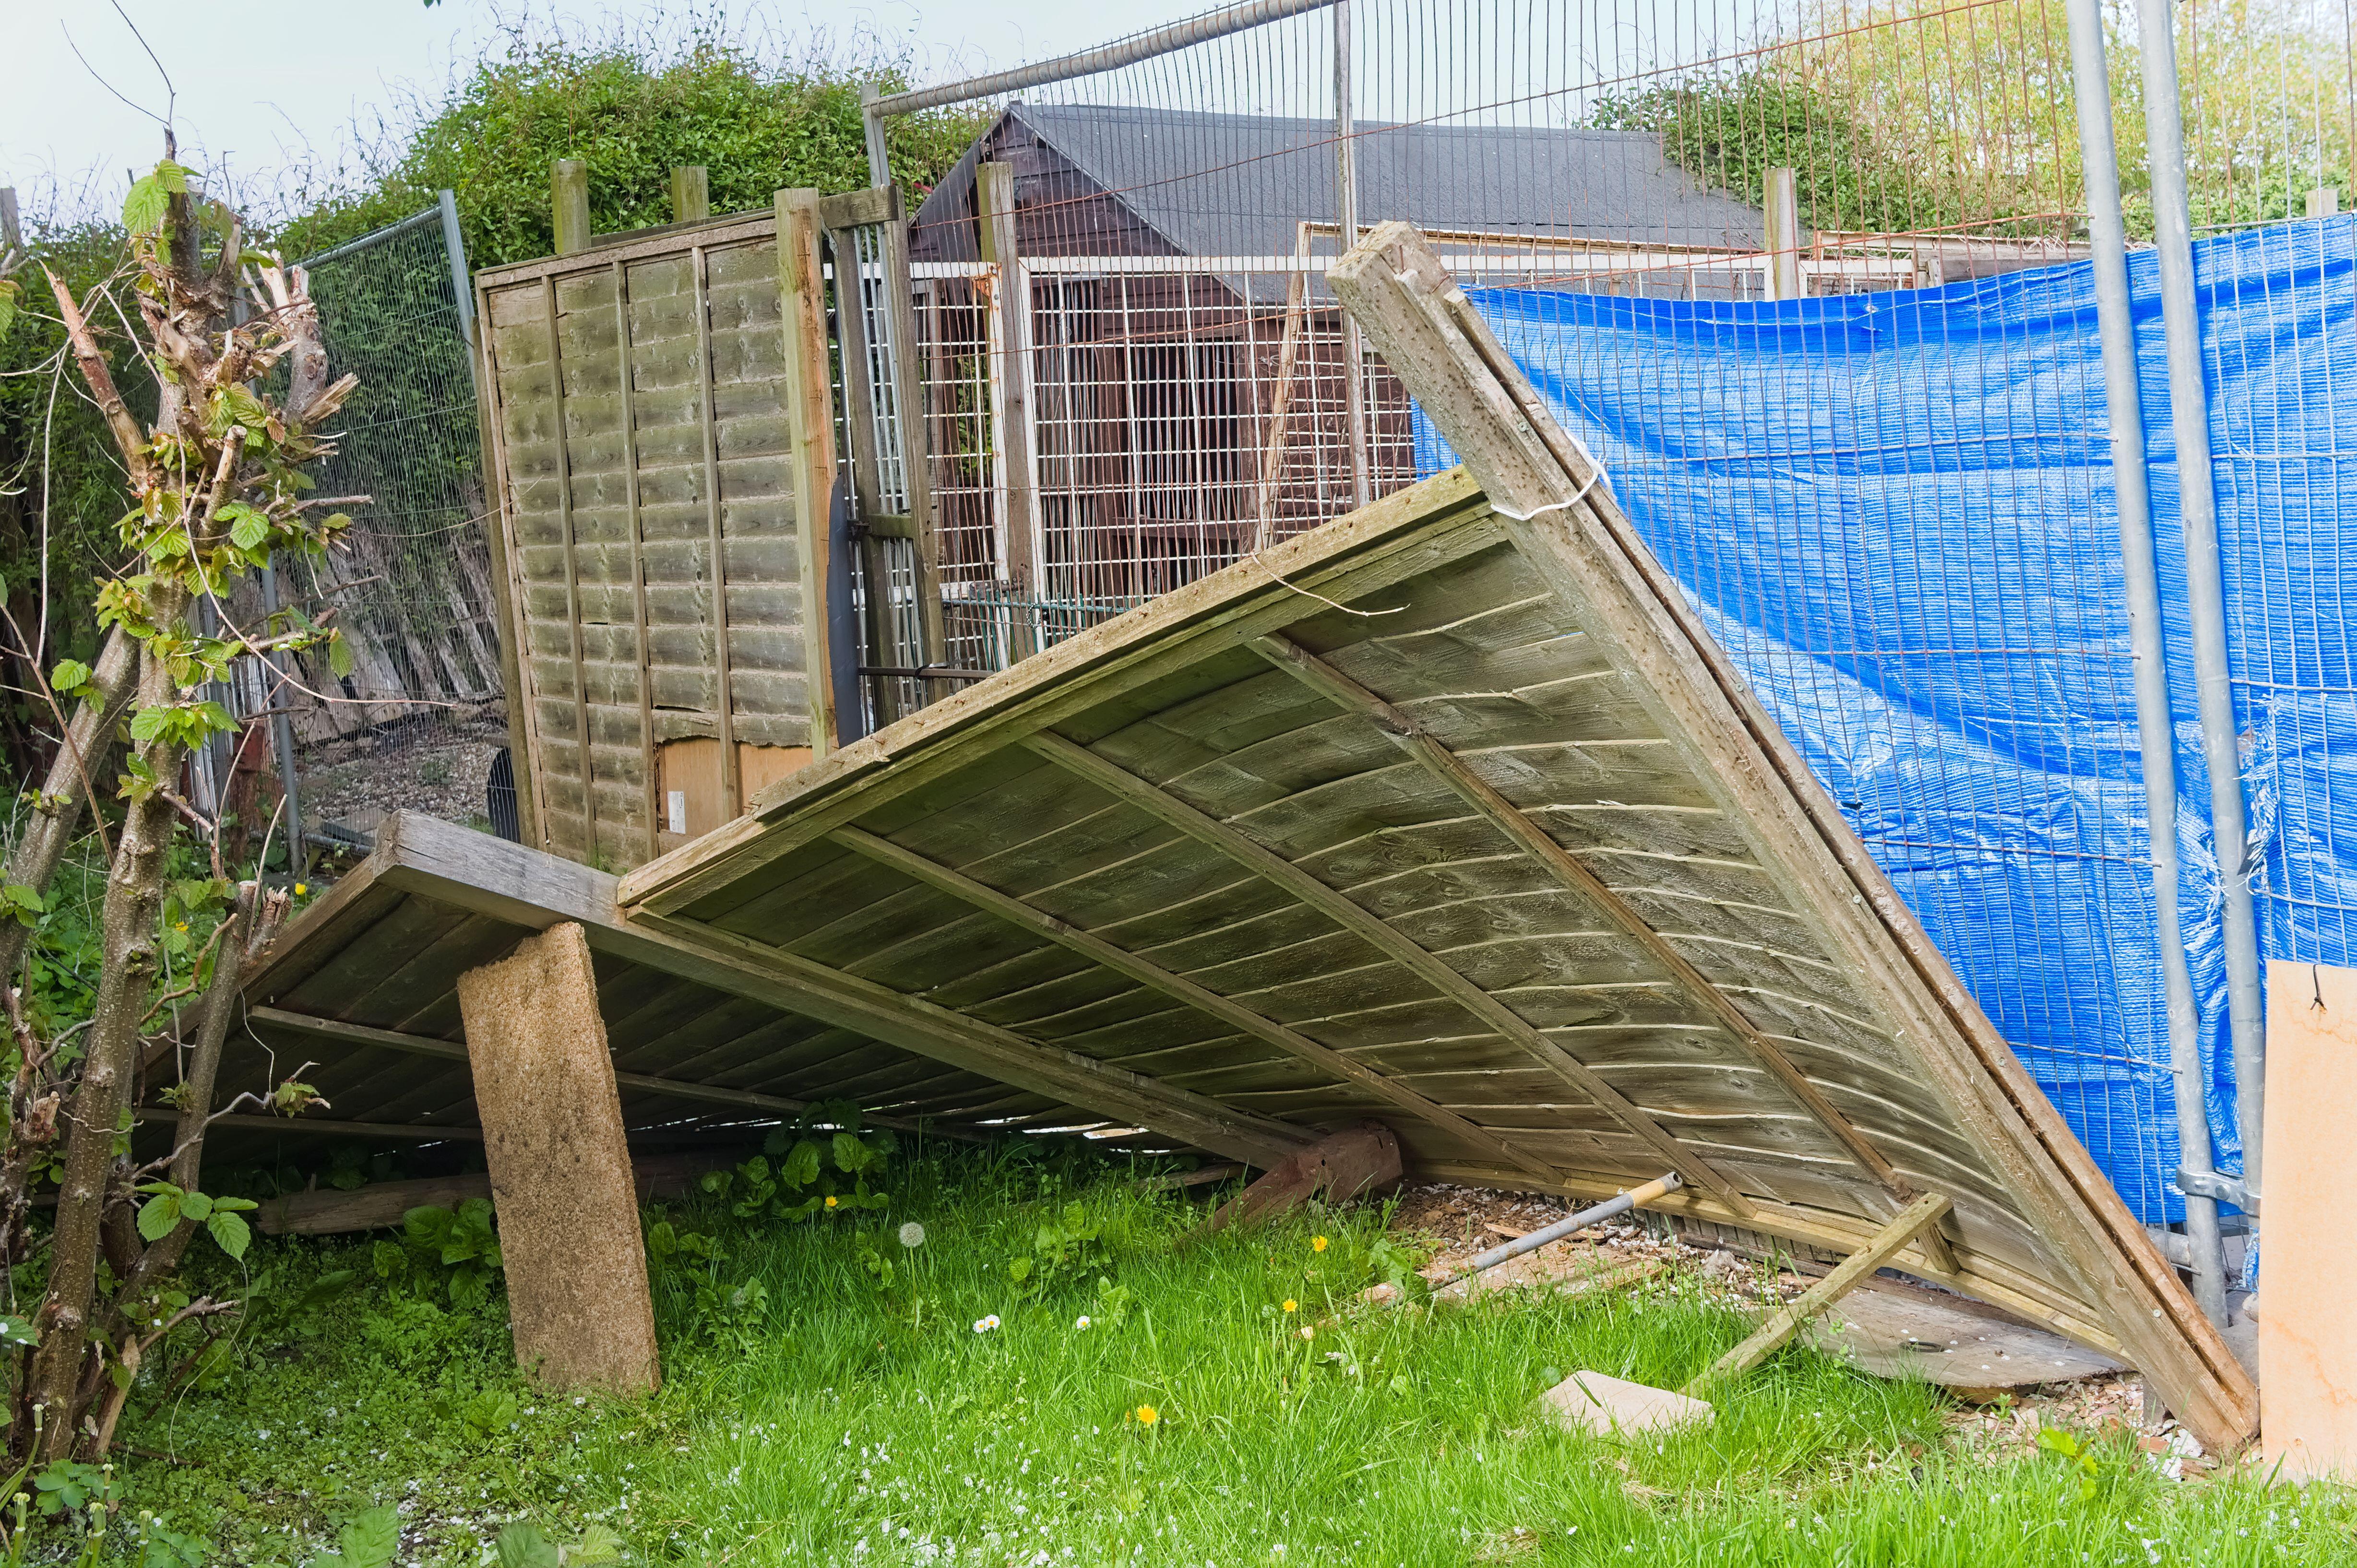
“Our data tells us that 99% of policies don’t cover damaged fences from storms, so you’d have to pay to fix them yourself,” the insurance expert reveals.
“When it comes to storms generally, each insurer has a different definition and they might dictate the wind speed that classifies it as a storm. If your claim doesn’t fall under their definition, it might be rejected.”
Myth 8: I’m covered if I run a side hustle from my spare room at home
Although standard home insurance usually covers remote or hybrid employees doing basic desk work, running a side hustle often requires separate business cover
“You will need specific business insurance if you’re running a business from home because the risks are different,” says Metcalfe.
“For example, if you keep stock or expensive business equipment in your house or have clients visiting the property, you’d also need public liability cover.”
Myth 9: I can take in a lodger or start renting on Airbnb on my standard cover
“If you host paying guests through something like an Airbnb, you’ll need specialist cover because when you rent out a property to short-term guests, insurers see it as a different kind of risk,” explains Metcalfe.
“Standard home insurance doesn’t cover guest-related damage or liability claims.”
Myth 10: All the plants in my garden will be covered from theft
“People are often surprised to find out that although their plants in pots are covered, plants in flower beds are not,” says Metcalfe. “So, if someone pulled the bay tree out of the flower bed and ran off with it, you wouldn’t be able to claim, but you would if it was in a plant pot.”
She adds: “If you’ve got a really expensive lawn mower which you keep in your shed, and you haven’t locked the shed and it gets stolen, your claim is likely to be rejected.”

